Encyclopedia of American Governance
American Guaranteed Investment System: Safe Returns, FDIC Protection, Treasury Bonds and Inflation Protection
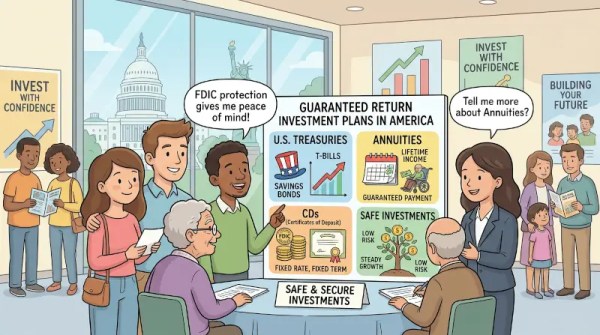
In the United States, a Guaranteed Return Investment Plan refers to a structured method of preserving capital and obtaining a predetermined, legally protected, or contractually guaranteed return through U.S. government securities, federally insured bank deposits, credit-union deposits, and insurance-backed financial contracts, rather than relying primarily upon volatile equity markets. The American system does not have one universal product called a “Guaranteed Return Investment Plan”; instead, it consists of several legally distinct mechanisms in which the source of the guarantee, duration of the guarantee, taxation, liquidity, and protection against inflation differ. The principal instruments are U.S. Treasury securities, Certificates of Deposit (CDs), federally insured savings accounts, Series I Savings Bonds, Treasury Inflation-Protected Securities (TIPS), fixed annuities, and certain stable-value retirement arrangements.
The monetary environment of 2026 has made guaranteed-return instruments particularly significant. Following the Federal Reserve’s benchmark-rate adjustment in late September 2026, with the federal funds target range stated at approximately 3.75%–4.00%, relatively high yields remained available in government and bank fixed-income instruments. In the market conditions described for October 2026, Treasury and bank products could offer returns broadly within the 4%–5% range, creating an unusual environment in which an investor could obtain substantial nominal income without accepting ordinary stock-market volatility. The precise yield available to an investor changes continuously according to maturity, auction conditions, institution, credit structure and monetary policy; consequently, an advertised rate should always be distinguished from the legally guaranteed principal or contractual rate.
The most direct form of American guaranteed investment is represented by U.S. Treasury securities, because these are direct obligations of the federal government. Treasury Bills (T-Bills) are short-term government securities, commonly issued with maturities such as 4, 8, 13, 26 and 52 weeks. They are normally purchased below face value and mature at face value, with the difference representing the investor’s return. Treasury Notes (T-Notes) generally cover maturities from approximately two through ten years and pay stated interest at regular intervals. Treasury Bonds (T-Bonds) extend the maturity structure to approximately twenty or thirty years. The essential mechanism is therefore a direct lending relationship between the investor and the United States Treasury.
Treasury securities possess two separate characteristics that are frequently confused. When held until maturity, the security provides the contractual repayment structure of the Treasury obligation. If the investor sells before maturity, however, the market price can rise or fall according to prevailing interest rates. Thus, the guarantee of payment at maturity is not a guarantee that the security can always be sold at its original purchase price. Long-term Treasury securities are particularly sensitive to interest-rate movements. The investor must therefore distinguish credit risk, which is exceptionally low for U.S. government obligations, from interest-rate and market-value risk.
Treasury securities also possess a major taxation advantage. Interest on U.S. Treasury obligations is generally subject to federal income taxation but exempt from state and local income taxes. This makes Treasury securities particularly attractive to investors residing in high-tax jurisdictions such as California, New York or New Jersey. A bank CD with a nominally higher interest rate may nevertheless produce a lower after-tax return than a Treasury security when state taxation is taken into account.
Series I Savings Bonds (I Bonds) constitute another government-backed instrument. Their structure combines a fixed rate with an inflation component, with the composite rate adjusted periodically according to the applicable inflation formula. Their purpose is not simply to maximize nominal interest but to provide a government-backed savings mechanism whose return responds to inflation. Treasury Inflation-Protected Securities (TIPS) serve a related but distinct function. TIPS adjust their principal according to movements in the Consumer Price Index (CPI), thereby providing an important mechanism for protecting long-term purchasing power from inflation.
The second major category is the Certificate of Deposit (CD). A CD is a bank deposit in which an investor agrees to leave money with the institution for a specified period in return for a stated interest rate. Terms can range from approximately one month to several years. In the market conditions supplied for October 2026, competitive institutional offers were described as reaching approximately 5.10% APY for selected multi-year products, while other high-rate providers were around 4.95% APY, with top one-year CD rates described around 4.40%–4.50%. These figures are market examples rather than permanent rates; CD rates change as institutions adjust their funding requirements and as monetary conditions change.
The principal safety mechanism for qualifying bank deposits is Federal Deposit Insurance Corporation (FDIC) protection. The standard statutory coverage is $250,000 per depositor, per insured institution, per ownership category. A similar federal protection system applies to qualifying deposits at federally insured credit unions through the National Credit Union Administration (NCUA). Covered deposit products generally include checking accounts, savings accounts, Money Market Deposit Accounts and CDs. Stocks, mutual funds, corporate bonds, cryptocurrency and life-insurance policies are not transformed into FDIC-insured assets merely because they are purchased through a bank.
This insurance limit is central to the construction of large guaranteed portfolios. An investor with $1 million should not ordinarily assume that placing the entire amount in one ordinary FDIC-insured bank automatically produces $1 million of federal deposit protection. Instead, investors can use different ownership categories or distribute qualifying deposits among appropriately insured institutions, subject to the applicable rules. This produces the multi-bank CD ladder, in which capital is divided among several maturities and institutions.
A High-Yield Savings Account (HYSA) occupies the liquid end of the same safety spectrum. Unlike a CD, the money is generally not locked for a predetermined maturity. Its principal can remain federally insured when held at an eligible FDIC-insured bank, but its interest rate is normally variable rather than fixed. In the October 2026 framework supplied, HYSAs were described as offering approximately 3.00%–4.50% APY, depending upon institution and market conditions. The HYSA therefore functions primarily as a liquidity instrument, rather than a permanent rate-locking instrument.
The insurance sector creates a third guarantee mechanism through fixed annuities. A fixed annuity is an insurance contract under which the issuing insurer can guarantee a specified interest rate for a defined period or provide a contractual income stream. It is sometimes compared to an insurance-based CD, but the legal structure is fundamentally different. The guarantee depends upon the claims-paying ability of the insurance company, not FDIC insurance. Some annuities are designed to accumulate capital; others are designed to convert capital into a predetermined lifetime or period-certain income.
This distinction becomes important in retirement planning. A person approaching retirement may allocate a portion of capital to a period-certain fixed annuity to create predictable income for a defined number of years. For example, an individual aged 62 who plans to retire at 65 but intends to delay Social Security until age 70 could potentially use a portion of retirement capital to create a five-year income bridge. A hypothetical $200,000 allocation to a suitable five-year contractual income product could be structured to provide a predetermined monthly payment. The precise payment, however, depends upon the contract, interest rate, age, payment structure, fees and insurer; the figure of approximately $3,800 per month in the supplied example is therefore an illustration rather than a universal annuity rate.
Stable Value Funds provide another specialized safety structure, particularly inside employer-sponsored 401(k) retirement plans. They generally hold high-quality fixed-income assets and employ insurance-company “wrapper” contracts or similar arrangements intended to provide stable participant values and predictable short-term returns. Their guarantees, liquidity provisions and withdrawal restrictions depend on the individual retirement plan and contractual structure.
The fundamental difference among these instruments can be represented as follows:
| Investment Type | Approximate October 2026 Yield Framework | Guarantee Mechanism | Liquidity |
|---|---|---|---|
| U.S. Treasuries | 4.00%–4.87% in supplied framework | U.S. government obligation | High, subject to market value if sold early |
| Certificates of Deposit | 4.00%–5.10% | FDIC/NCUA insurance within limits | Low to moderate; early-withdrawal penalties may apply |
| High-Yield Savings | 3.00%–4.50% | FDIC/NCUA deposit insurance | High |
| Fixed Annuities | Approximately 4.00%–5.00% in supplied framework | Insurer’s contractual obligation | Very low in many structures |
| TIPS/I Bonds | Inflation-linked | U.S. government | Subject to applicable redemption rules |
The practical architecture of a guaranteed-return plan depends principally upon time horizon. Money required within six months should generally remain in a highly liquid insured savings account or suitable short-term Treasury instrument. Money required in one or two years can be matched with CDs or Treasury securities whose maturity corresponds with the expenditure date. Capital intended for three to ten years may be divided among Treasury Notes, longer CDs and other fixed-income instruments. Retirement capital may additionally incorporate fixed annuities or stable-value arrangements where their contractual terms are appropriate.
A $50,000 house-down-payment fund demonstrates the principle. If the money is required in approximately eighteen months, the investor might place $10,000 in an HYSA, $20,000 in a 12-month CD, and $20,000 in an 18-month CD. At the illustrative rates supplied—approximately 4.25%, 5.10% and 4.95%, respectively—the structure seeks to combine immediate liquidity with fixed-rate growth. The supplied calculation places the approximate eighteen-month interest generation around $3,600, although actual results depend upon compounding conventions, taxes, precise rates and timing.
A second model applies to a high-tax-bracket investor. Suppose $100,000 is intended to remain safe for several years and the investor resides in a state with substantial income taxation. A Treasury Note yielding 4.85% would produce approximately $4,850 of annual gross interest. If a comparable bank deposit generated the same nominal amount but were subject to a hypothetical 10% state income tax, approximately $485 could be lost to state taxation. Treasury interest’s state-and-local tax exemption can therefore create a meaningful after-tax advantage.
A third model is the retirement-income bridge, where the purpose of the investment is not merely capital accumulation but predictable cash flow. Here the investor evaluates the amount of income required, the duration of the bridge, Social Security timing, pension income, taxes and the contractual terms of the annuity or Treasury portfolio.
The distinction between locking in a return and remaining liquid is one of the central principles of guaranteed investing. A one-year CD can lock a fixed APY but may impose an early-withdrawal penalty. A Treasury security can be sold before maturity, but its market price may be below the investor’s purchase price. An HYSA permits easier access but normally carries a variable interest rate. A fixed annuity may provide stronger long-term contractual income but can impose surrender restrictions. There is therefore no instrument that simultaneously provides maximum yield, unlimited liquidity, permanent rate certainty and complete inflation protection.
For a hypothetical $100,000, the supplied October 2026 framework compares a 10-year Treasury Note at approximately 5.28%, a one-year CD at approximately 4.50%, and an HYSA at approximately 4.00%. At those illustrative rates, the gross annual amounts would be approximately $5,280, $4,500 and $4,000, respectively. The Treasury’s attraction is long-term rate locking and state-tax exemption; the CD’s attraction is fixed short-term maturity; and the HYSA’s attraction is immediate accessibility. The numerical comparison demonstrates why yield alone cannot determine the correct investment.
The corresponding execution blueprint is therefore:
Cash Capital → 0–6 Month Emergency Need → HYSA
Cash Capital → 1–2 Year Fixed Goal → CD or Treasury Bill
Cash Capital → 3–10 Year Capital Preservation → Treasury Notes
Retirement Capital → Guaranteed Income Requirement → Fixed Annuity or appropriate Treasury ladder
For institutional and corporate investors, the same principles operate on a larger scale. Corporations, partnerships, trusts, estates and other entities may use Treasury bills, institutional deposit arrangements and insured cash-management structures to preserve temporary excess cash. Businesses frequently use short-term government securities because their operating cash may need to remain safe while still producing income.
The American guaranteed-investment framework is also relevant to foreign investors, although access differs according to residency, tax status and account eligibility. U.S. citizens and eligible residents with the required identification and address documentation can generally access domestic banking and Treasury investment channels subject to applicable rules. A non-resident foreign investor living outside the United States may face different eligibility requirements for TreasuryDirect and therefore may acquire Treasury securities through an eligible international brokerage or secondary-market channel. Such investors may also encounter U.S. tax documentation requirements such as IRS Form W-8BEN. Brokered CDs can provide another channel, although the investor must verify the legal ownership structure, issuing institution and applicability of deposit insurance.
The statement that “anyone” can use an American guaranteed-return plan must therefore be understood carefully. Citizenship is not itself the only determinant of eligibility. Residency, tax identification, account-opening requirements, broker eligibility, banking rules and the specific product’s contractual restrictions determine access. The legal protection attached to an investment depends upon the investor’s actual ownership and the product’s qualifying status.
Three broad portfolio architectures emerge from the American system. The Liquid Sovereignty Portfolio emphasizes government obligations, with a hypothetical allocation of 40% short-term T-Bills and 60% medium-term Treasury Notes, seeking sovereign credit protection and state-tax advantages. The Multi-Bank CD Ladder Portfolio might allocate 25% to an HYSA, 25% to a six-month CD, 25% to a one-year CD and 25% to a two-year CD, distributing deposits where necessary to remain within applicable insurance limits. The Inflation-Proof Wealth Preservation Portfolio can emphasize 50% TIPS, 30% Series I Savings Bonds and 20% high-quality municipal securities, although municipal bonds do not carry the same federal guarantee as Treasury securities and therefore should not be described as absolutely risk-free.
The final distinction is between nominal safety and real safety. A guaranteed $100,000 remains $100,000 in nominal terms, but if inflation substantially reduces purchasing power, the investor may nevertheless become poorer in real terms. This is why TIPS and I Bonds occupy an important position in the American guaranteed-return architecture. Similarly, a high nominal rate may lose its advantage after federal, state and local taxation.
A genuine American guaranteed-return investment plan is therefore an architecture of legal guarantees rather than a promise of effortless profit. U.S. Treasuries provide sovereign backing; CDs and qualifying deposits provide federal insurance within statutory limits; HYSAs provide liquid insured savings with variable rates; I Bonds and TIPS address inflation; fixed annuities provide insurance-company contractual guarantees; and stable-value funds provide specialized retirement-plan protection. The investor’s task is to align guarantee, maturity, liquidity, taxation, inflation exposure and income requirements. The strongest plan is consequently not necessarily the one with the highest advertised APY, but the one in which the source of the guarantee, duration of the guarantee, tax treatment and date of required liquidity are deliberately matched to the investor’s objective.
Read more
- Easy Loans in America: U.S. Personal Loans, Credit, Rates and Lenders
- EB-5 Investment for Chinese Nationals: $800k Projects and Visa Options 2026
Sarvarthapedia Conceptual Node: Guaranteed Return Investment Plan in America
Core Node: Guaranteed Return Investment Plan in America
Central Question: How can capital in the United States be preserved while generating a legally protected, federally insured, sovereign-backed, or contractually guaranteed return?
Primary Conceptual Chain:
Capital Preservation → Guarantee Mechanism → Fixed Return → Liquidity → Taxation → Inflation → Income Generation → Retirement Security → Wealth Preservation
Cluster 1: Sovereign Guarantee
U.S. Treasury Securities
Guaranteed Return Investment Plan
→ U.S. Government Debt
→ Treasury Securities
→ Treasury Bills
→ Treasury Notes
→ Treasury Bonds
Conceptual relationship:
Investor Capital → U.S. Treasury → Government Obligation → Interest → Maturity → Principal Repayment
Treasury Bills
T-Bills
→ Short-Term Capital Preservation
→ 4–52 Week Maturity
→ Discount Purchase
→ Face-Value Redemption
→ Liquidity Management
Treasury Notes
T-Notes
→ Medium-Term Capital Preservation
→ 2–10 Year Maturity
→ Periodic Interest
→ Income Distribution
Treasury Bonds
T-Bonds
→ Long-Term Capital Lock-In
→ 20–30 Year Maturity
→ Fixed Income
→ Long-Term Wealth Preservation
Cluster 2: Federal Deposit Insurance
Certificates of Deposit
Guaranteed Return Plan
→ Bank Deposit
→ Certificate of Deposit
→ Fixed Term
→ Fixed Interest Rate
→ Maturity
→ Principal + Interest
CD → Fixed Return → Reduced Liquidity → Early Withdrawal Penalty
FDIC Insurance
CD
→ FDIC Insurance
→ $250,000 Standard Coverage
→ Depositor
→ Insured Institution
→ Ownership Category
The crucial conceptual distinction is:
Bank Guarantee ≠ Government Debt Guarantee
A Treasury security represents a direct government obligation, while an eligible CD is a bank deposit protected by federal deposit insurance within applicable limits.
NCUA Protection
Credit Union Deposit
→ NCUA Insurance
→ Federal Deposit Protection
→ CD / Share Certificate
→ Capital Preservation
FDIC → Banks
NCUA → Credit Unions
Cluster 3: Liquid Guaranteed Savings
High-Yield Savings Account
HYSA
→ Federally Insured Deposit
→ Variable Interest Rate
→ High Liquidity
→ Emergency Reserve
→ Short-Term Capital
HYSA → Liquidity
CD → Rate Lock
This produces a fundamental conceptual opposition:
Liquidity ↔ Yield Lock-In
Cluster 4: Inflation Protection
Inflation Risk
Guaranteed Nominal Return
→ Inflation
→ Purchasing-Power Erosion
→ Real Return
Nominal Guarantee ≠ Real Wealth Guarantee
Series I Savings Bonds
I Bonds
→ U.S. Government
→ Fixed Component
→ Inflation Component
→ Composite Rate
→ Purchasing-Power Protection
Treasury Inflation-Protected Securities
TIPS
→ Treasury Securities
→ CPI Adjustment
→ Inflation-Adjusted Principal
→ Real-Value Preservation
Inflation → CPI → TIPS → Adjusted Principal
Inflation → I Bonds → Composite Interest Rate
Cluster 5: Insurance-Backed Guarantees
Fixed Annuities
Fixed Annuity
→ Insurance Contract
→ Fixed Interest
→ Contractual Guarantee
→ Accumulation
→ Income Stream
→ Retirement Planning
Bank CD → FDIC Protection
Fixed Annuity → Insurer’s Claims-Paying Ability
Therefore:
FDIC Guarantee ≠ Insurance-Company Guarantee
Period-Certain Annuity
Retirement Capital
→ Fixed Annuity
→ Period-Certain Income
→ Monthly Cash Flow
→ Retirement Income Bridge
Retirement Age → Income Gap → Annuity → Predictable Cash Flow
Cluster 6: Retirement Security
Retirement Income
Guaranteed Investment
→ Capital Preservation
→ Income Generation
→ Retirement Security
401(k)
→ Stable Value Fund
→ Insurance Wrapper
→ Stable Account Value
→ Retirement Capital Preservation
Social Security Bridge
Retirement at 65
→ Delayed Social Security
→ Five-Year Income Requirement
→ Fixed Annuity / Treasury Ladder
→ Guaranteed Cash Flow
Retirement Capital → Income Bridge → Social Security Optimization
Cluster 7: Tax Architecture
Treasury Tax Advantage
Treasury Interest
→ Federal Taxation
→ State and Local Tax Exemption
→ Higher After-Tax Yield
Bank Deposit Taxation
CD Interest / HYSA Interest
→ Ordinary Taxable Income
→ Federal Tax
→ Potential State Tax
→ Reduced Net Return
The conceptual relationship is:
Nominal Yield → Tax → After-Tax Yield
Therefore:
5% Taxable CD ≠ 5% Tax-Exempt Treasury
when the investor is subject to state income taxation.
Cluster 8: Time-Horizon Architecture
Short-Term Capital
0–6 Months
→ Emergency Fund
→ HYSA
→ T-Bills
→ Maximum Liquidity
Medium-Term Capital
1–2 Years
→ Known Financial Goal
→ CD
→ T-Bills
→ Maturity Matching
Long-Term Capital
3–10 Years
→ Treasury Notes
→ CD Ladder
→ Fixed Income
→ Capital Preservation
Retirement Capital
5+ Years
→ Treasury Ladder
→ Fixed Annuity
→ TIPS
→ Stable Value
→ Retirement Income
Time Horizon → Instrument Selection
Cluster 9: CD Ladder Architecture
CD Ladder
Cash Capital
→ Multiple CDs
→ Multiple Maturities
→ Periodic Maturity
→ Reinvestment
→ Liquidity Management
6-Month CD → 1-Year CD → 2-Year CD → 3-Year CD
The ladder transforms:
Single Maturity Risk → Distributed Maturity Risk
It also creates:
Maturity → Cash Availability → Reinvestment Decision
Cluster 10: Treasury Ladder Architecture
Treasury Ladder
Capital
→ T-Bills
→ 2-Year Note
→ 3-Year Note
→ 5-Year Note
→ 10-Year Note
Maturity Diversification → Interest-Rate Management → Liquidity
The Treasury ladder connects directly to:
Yield Curve → Interest Rates → Federal Reserve → Monetary Policy
Cluster 11: Federal Reserve and Interest Rates
Federal Funds Rate
Federal Reserve
→ Federal Funds Rate
→ Bank Funding Cost
→ CD Rates
→ Savings Rates
→ Treasury Yields
→ Fixed-Income Returns
Monetary Policy → Interest Rates → Guaranteed-Investment Yields
A rate-hiking environment can increase the attractiveness of newly issued CDs, Treasury securities and savings products, while a rate-cutting environment can increase the value of previously locked-in fixed rates.
Cluster 12: Liquidity Versus Yield
Liquidity
HYSA → High Liquidity → Variable Yield
Lock-In
CD → Fixed Yield → Early Withdrawal Penalty
Market Liquidity
Treasury → Secondary Market → Sale Before Maturity → Market Price Risk
Contractual Illiquidity
Annuity → Surrender Period → Long-Term Commitment
The conceptual network becomes:
Liquidity ↑ → Rate Certainty ↓
Rate Lock-In ↑ → Liquidity ↓
Cluster 13: Risk Architecture
Credit Risk
Who owes the money?
U.S. Treasury → Sovereign Obligation
Bank CD → Depository Institution + FDIC
Annuity → Insurance Company
Market Risk
Treasury Sold Before Maturity → Market Price Fluctuation
Inflation Risk
Nominal Return → Inflation → Real Return
Liquidity Risk
Long-Term Lock-In → Difficulty Accessing Capital
Tax Risk
Gross Yield → Tax Liability → Net Yield
Institutional Risk
Bank / Insurer → Financial Strength → Guarantee Capacity
Cluster 14: $100,000 Allocation Architecture
Government Model
$100,000 → Treasury Securities
40% → Short-Term T-Bills
60% → 2–5 Year Treasury Notes
→ Sovereign Safety
→ State/Local Tax Advantage
→ Maturity Diversification
CD Model
$100,000 → Multi-Bank CD Ladder
25% → HYSA
25% → 6-Month CD
25% → 1-Year CD
25% → 2-Year CD
→ FDIC/NCUA Protection
→ Fixed Rates
→ Periodic Liquidity
Inflation Model
$100,000 → Inflation-Protected Portfolio
50% → TIPS
30% → I Bonds
20% → High-Quality Municipal Securities
→ Inflation Protection
→ Government-Linked Assets
→ Purchasing-Power Preservation
Cluster 15: High-Tax-State Strategy
State Tax
California / New York / New Jersey
→ High State Income Tax
→ Taxable CD Interest
→ Lower After-Tax Return
Treasury Interest
→ State/Local Tax Exemption
→ Effective Yield Advantage
High Tax Rate → Treasury Preference
Cluster 16: Foreign Investor Architecture
U.S. Citizen / Resident
SSN / ITIN + Eligible Address
→ U.S. Banking
→ Treasury Access
→ CDs
→ Government Securities
Non-Resident Investor
Foreign Investor
→ International Brokerage
→ Treasury Secondary Market
→ Brokered CDs
→ Tax Documentation
→ W-8BEN
Global Capital → U.S. Financial System → Sovereign Debt
Cluster 17: Corporate Treasury Management
Corporate Cash
Corporate Surplus Cash
→ Cash Management
→ T-Bills
→ Institutional Deposits
→ Sweep Accounts
→ Capital Preservation
Business Operations → Temporary Excess Cash → Short-Term Government Securities
This connects the personal-investment node to:
Corporate Finance → Treasury Management → Working Capital → Liquidity Management
Cluster 18: Guaranteed Return Versus Market Investment
Guaranteed-Return Assets
Treasuries / CDs / HYSAs / Fixed Annuities
→ Predictability
→ Capital Protection
→ Lower Volatility
→ Limited Upside
Market Assets
Stocks / Equity Funds / Index Funds
→ Market Risk
→ Capital Appreciation Potential
→ Higher Volatility
→ No Guaranteed Principal
Core conceptual opposition:
Capital Certainty ↔ Growth Uncertainty
Guaranteed Return ↔ Market Return
Nominal Stability ↔ Capital Appreciation
Cluster 19: Real Return Architecture
Nominal Return
APY → Dollar Growth
Real Return
APY − Inflation → Purchasing-Power Growth
After-Tax Real Return
Nominal Yield − Tax − Inflation
This creates one of the most important Sarvarthapedia conceptual chains:
Gross Return → Tax → Inflation → Real After-Tax Return
A product advertised as “guaranteed” can therefore guarantee the nominal contractual return without guaranteeing that the investor becomes wealthier in real purchasing-power terms.
Cluster 20: Core See-Also Knowledge Web
Direct See Also
See also:
U.S. Treasury Securities
↔ Treasury Bills
↔ Treasury Notes
↔ Treasury Bonds
↔ TreasuryDirect
↔ Federal Reserve
↔ Interest Rates
↔ Yield Curve
Certificates of Deposit
↔ FDIC Insurance
↔ NCUA
↔ Banking
↔ Deposit Insurance
↔ CD Ladder
High-Yield Savings Accounts
↔ Emergency Fund
↔ Liquidity Management
↔ Variable Interest Rates
Fixed Annuities
↔ Retirement Planning
↔ Guaranteed Income
↔ Insurance Companies
↔ Period-Certain Annuity
TIPS
↔ Inflation
↔ Consumer Price Index
↔ Real Return
↔ Purchasing Power
I Bonds
↔ Inflation Protection
↔ Savings Bonds
↔ Treasury Securities
Cluster 21: Higher Sarvarthapedia Conceptual Network
Guaranteed Return Investment Plan
→ Capital Preservation
→ Financial Security
→ Income Certainty
→ Risk Management
→ Tax Optimization
→ Inflation Protection
→ Retirement Security
→ Wealth Preservation
→ Intergenerational Capital
These connect upward to:
Personal Finance → Financial Economics → Monetary Economics → Banking System → U.S. Treasury System → Federal Reserve System → Insurance System → Retirement System
Cluster 22: Meta-Civilizational Position
Money as a Civilizational Information System
Capital
→ Stored Economic Value
→ Financial Contract
→ Legal Guarantee
→ Institutional Trust
→ State Power
→ Monetary System
→ Economic Civilization
The guaranteed-return system therefore represents more than a collection of savings products. It is a network connecting individual capital to banks, insurance companies, the U.S. Treasury, federal taxation, monetary policy, inflation measurement, retirement institutions and the legal enforcement of financial contracts.
At the highest conceptual level:
Individual Wealth → Financial Institution → Legal Contract → State Guarantee → Monetary System → Economic Stability
Master Sarvarthapedia Knowledge Graph
Guaranteed Return Investment Plan in America
↔ Capital Preservation
↔ U.S. Treasury
↔ Federal Reserve
↔ Interest Rate
↔ Yield Curve
↔ Treasury Bill
↔ Treasury Note
↔ Treasury Bond
↔ CD
↔ FDIC
↔ NCUA
↔ HYSA
↔ Fixed Annuity
↔ Stable Value Fund
↔ TIPS
↔ I Bonds
↔ Inflation
↔ CPI
↔ Real Return
↔ Taxation
↔ State Tax Exemption
↔ Liquidity
↔ Maturity
↔ CD Ladder
↔ Treasury Ladder
↔ Retirement Income
↔ Social Security
↔ Corporate Treasury
↔ Foreign Investment
↔ Risk Management
↔ Wealth Preservation
The central Sarvarthapedia relationship can therefore be expressed as:
Guarantee → Certainty → Capital Preservation → Income → Tax Efficiency → Inflation Management → Liquidity Management → Retirement Security → Long-Term Wealth Preservation
And its principal counter-network is:
Guarantee ↑ → Market Risk ↓ → Return Ceiling ↓
Liquidity ↑ → Rate Certainty ↓
Maturity ↑ → Interest-Rate Sensitivity ↑
Inflation ↑ → Real Return ↓
Taxation ↑ → After-Tax Return ↓
Diversification ↑ → Concentration Risk ↓
This Guaranteed Return Investment Plan in America a central node connecting American banking, sovereign debt, monetary policy, taxation, insurance, retirement finance, inflation economics and personal wealth management within the Sarvarthapedia knowledge architecture.